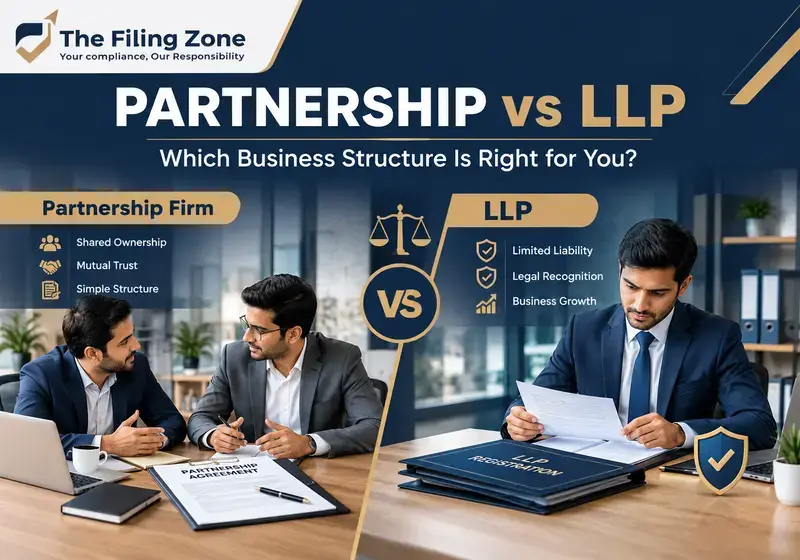
Partnership vs LLP: Which Business Structure Is Right for You? Differences, eligibility, benefits, compliance and how to decide
Last month, a client called me about a decision he had been putting off for six months. He and his brother were already running a successful stationery distribution business as a partnership. Orders were growing, a bank was offering a working capital limit, and a large buyer had asked, “Are you a company or a firm?” Suddenly, the question that had seemed like paperwork felt like a real decision: should they stay a partnership, or move to an LLP?
If you are standing at the same crossroads, this post is for you. I will keep the legal jargon light and focus on what actually changes in your life as an owner.
Starting with the basics
What is a partnership firm?
A partnership firm is governed by the Indian Partnership Act, 1932. Two or more people agree to run a business together and share the profits. That is it. You do not need a government certificate for it to exist, and even a verbal agreement can create one, though I would never recommend relying on that.
The catch is personal liability. In a partnership, the firm and its partners are not separate in the eyes of the law. If the business owes money it cannot pay, creditors can come after your personal assets, such as your house, savings or vehicle. And that liability is joint and several, which means one partner can be made to pay the whole debt, even if a different partner caused it.
What is an LLP?
A Limited Liability Partnership is governed by the LLP Act, 2008. Think of it as a hybrid. It works like a partnership on the inside, with flexible rules set by an agreement between partners, but it is a separate legal entity, like a company, on the outside.
That one change, a separate legal identity, is what makes the difference. An LLP can own property, sign contracts and sue or be sued in its own name. And your personal assets are generally protected. Your liability is limited to the amount you agreed to contribute, except in cases of fraud or wrongful acts by you.
The key differences, side by side
|
Point |
Partnership Firm |
LLP |
|
Governing law |
Indian Partnership Act, 1932 |
LLP Act, 2008 |
|
Registration |
Optional |
Compulsory, with the Registrar of Companies (ROC) |
|
Legal identity |
Not separate from partners |
Separate legal entity |
|
Liability of partners |
Unlimited, joint and several |
Limited to agreed contribution |
|
Minimum partners |
2 |
2 (with at least 2 designated partners) |
|
Maximum partners |
50 |
No upper limit |
|
Perpetual succession |
No, ends with certain events like death or retirement unless the deed says otherwise |
Yes, continues despite changes in partners |
|
Annual filings with ROC |
None |
Compulsory (Form 11 and Form 8) |
|
Audit |
Only if tax audit limits are crossed |
Based on turnover or contribution limits, and tax audit if applicable |
|
Setup cost and effort |
Low |
Moderate |
|
Credibility with large clients and lenders |
Moderate |
Higher |
|
Raising funds from outside investors |
Difficult |
Easier than a partnership, though less common than for companies |
Two rows deserve a closer look.
Registration. A partnership can run without any registration, though that costs you the right to sue in many situations. An LLP cannot exist without incorporation with the ROC.
Compliance. This is the price of limited liability. Partnerships have almost no annual ROC work. LLPs must file two forms every year, even when there is no business activity.
Who can start each one?
Eligibility for a partnership
- At least two persons, and no more than 50 for a business partnership.
- Every partner must be an adult (18 or above) of sound mind, and legally allowed to enter a contract.
- A minor can be admitted only to the benefits of the partnership, not as a full partner.
- Individuals can be partners. Companies and other firms usually cannot be partners in a general partnership.
Eligibility for an LLP
- At least two individuals or bodies corporate, with no upper limit on the number of partners.
- At least two designated partners, who must be individuals. They carry the compliance responsibilities.
- At least one designated partner must be resident in India. Resident means staying in India for 120 days or more in the previous year.
- Every designated partner needs a Designated Partner Identification Number (DPIN), and a digital signature certificate.
- A company or another LLP can be a partner, but it must nominate an individual to act as designated partner.
- NRIs and foreign nationals can be partners, but investment rules under FEMA apply, and some sectors are restricted.
One more point: not every business can use an LLP. Certain regulated areas, such as banking and insurance, need other structures. Some professions and sectors have special rules, so please check before you decide.
Benefits of a partnership
I do not want to give partnerships a bad name. For the right business, they are still a good choice.
It is cheap and quick. A stamp-paper deed and a PAN, and you are ready to start.
Compliance is light. No annual ROC filings. Your main duties are your books, tax returns and GST if applicable.
It is flexible and private. Internal rules can be changed by mutual agreement, and nothing about your capital or partners is published on a public register.
It suits family businesses and small trading outfits where owners know each other, risk is low, and nobody plans to bring in outside investors.
Benefits of an LLP
Limited liability. This is the big one. If the business fails, your personal assets are generally safe, apart from your agreed contribution and cases of fraud.
Perpetual succession. The business does not end because a partner dies, retires or leaves. That gives clients, banks and employees a sense of stability.
No cap on partners and no minimum capital. You decide the contribution, and you can start small.
Better image. Many large buyers, tender departments and lenders feel more comfortable with an LLP than with a basic firm.
Easier to bring in new partners and exit old ones. Changes are handled through filings with the ROC under the LLP agreement.
Tax-neutral conversion route. If you start as a partnership, you can later convert to an LLP, and tax laws provide relief when conditions are met. I will return to this below.
Taxes: is one cheaper than the other?
For income tax, a partnership firm and an LLP are treated in a very similar way. An LLP pays a flat 30% on its total profit. Partnership firms are taxed at the same basic rate, along with applicable surcharge and cess. In both cases, the partners’ share of profit is not taxed again in their own hands.
Both can also pay salary and interest to working partners, but only within the limits of the Income Tax Act and only if the deed or agreement allows it. This is a point many people miss.
So you will not save tax simply by switching. What you do gain is protection. What you pay for it is compliance.
GST: the same for both
GST applies on turnover thresholds and other triggers, not on the type of entity. A partnership and an LLP are both treated as taxable persons, and both need registration if they cross the limit or fall under a mandatory category such as inter-state supply of goods or e-commerce selling. Both can also opt for the Composition Scheme if they qualify.
The compliance gap: what an LLP asks of you every year
This is where many people get surprised, so I will be direct.
- Form 11 (Annual Return). Filed under Section 35 of the LLP Act, due 30 May every year, and it covers the partner and contribution structure.
- Form 8 (Statement of Account and Solvency). This must be filed by every LLP regardless of size, turnover or profit. The due date is 30 October for the April to March financial year.
- Income tax return. It is usually due by 31 July if no audit applies, or by 31 October if audit applies.
- A statutory audit is required if turnover is over ₹40 lakh or contribution is over ₹25 lakh.
- DIR-3 KYC for designated partners each year.
Late filing carries a daily fee, and it can add up quickly. A silent LLP that files nothing for a few years can end up with large penalties and compliance problems. A partnership has no such problem, which is one reason many small owners prefer it.
Smaller LLPs get some relief. There is a concept of a small LLP with lower fees and lighter penalties, but filing deadlines still apply.
Which is better? My honest answer
There is no universal winner, and anyone who tells you otherwise is selling something. Here is how I usually guide people.
A partnership may suit you if:
- Your business is small, local and low-risk.
- The partners are family or very close friends.
- You do not carry big debts or contracts.
- You want the lowest cost and least paperwork.
An LLP is usually better if:
- You have significant turnover, loans, or large contracts.
- You deal with big clients, tender departments or lenders who want a formal entity.
- You are in a service or consulting business where one partner’s mistake could hurt everyone.
- You expect to add partners over time.
- You have personal assets, such as a house or savings, that you want to protect.
And a third option: if you are thinking about outside investors, a Private Limited Company may be better than either.
My rule of thumb: the more money you could lose, the more an LLP makes sense. If a bad year could cost you your home, pay the compliance cost for the protection.
What to do if you already have a partnership
Many of my clients start as a partnership and move to an LLP once the business is stable. The good news is that conversion is possible, and tax law provides relief from capital gains when certain conditions are met.
The process in outline:
- Reserve the LLP name with the ROC.
- Get DPINs and digital signatures for the designated partners.
- File the application for conversion in Form 17, which is the application and statement for converting a firm into an LLP.
- Prepare and file the LLP agreement within 30 days of incorporation.
- After conversion, update your PAN, GST, bank accounts, licences and contracts.
Plan this with your CA, because the tax conditions are strict. Missing one can turn a tax-free conversion into a tax event.
Documents you will need for an LLP
- PAN and Aadhaar of all partners
- Passport-size photographs
- Address proof of each partner (bank statement, utility bill or driving licence)
- Address proof of the registered office, with an NOC from the owner if rented
- Digital signature certificates for designated partners
- Proposed names for the LLP
- LLP agreement, to be filed within 30 days of incorporation
- For foreign or NRI partners, passport and apostilled or notarised address proof
For a partnership, the list is shorter: partner PAN and Aadhaar, photographs, business address proof and a stamped partnership deed.
Also Read 👉 Thinking of Starting a Business
Common mistakes I see
Choosing an LLP without budgeting for compliance. Keep a yearly provision for audit, filing and professional fees.
Forgetting the LLP agreement. Without a filed agreement, the default rules of the LLP Act apply, and they may not match what you intended.
Treating a partnership as safe because “we trust each other.” Trust does not protect your house from a creditor.
Ignoring DIR-3 KYC and annual filings. Your DPIN can be deactivated and penalties can pile up.
Mixing personal and business money. This is a bad habit in any structure, but in an LLP it can damage the limited liability protection.
Conclusion
If you remember only one thing from this post, let it be this. A partnership is easy to start and easy to run, but it puts your personal wealth on the line. An LLP asks for more discipline, but it lets you sleep better when the business grows.
Think about how much risk you carry, who your clients are, and where you want to be in five years. Then decide. If you are unsure, speak to a CA or company secretary before you sign anything, and make sure your agreement is in writing.
Disclaimer: This post is for general information. Thresholds, fees, due dates and tax rules change from time to time, so please check the current provisions or consult a professional before acting.
Read More About 👉 What Is a Partnership Firm
Frequently Asked Questions (FAQs)
Q1. What is the main difference between a partnership and an LLP?
An LLP is a separate legal entity with limited liability for partners. A partnership firm is not separate from its partners, and they carry unlimited personal liability.
Q2. Is registration compulsory for a partnership firm?
No. It is optional, though an unregistered firm faces limits on filing suits in court. An LLP, on the other hand, must be registered with the ROC.
Q3. How many partners are needed to form an LLP?
At least two.
Q4. Is there a limit on the number of partners in an LLP?
No. A partnership firm is limited to 50 partners, but an LLP has no upper limit.
Q5. Can an NRI or foreign national become a partner in an LLP?
Yes, subject to FEMA and sector-specific rules. At least one designated partner must be resident in India.
Q6. Which is cheaper to run, a partnership or an LLP?
A partnership. It has no mandatory ROC filings. An LLP needs annual filings, possible audit and professional fees, so running costs are higher.
Q7. Do I pay less tax as an LLP?
Not usually. Both are taxed at similar rates, and profit is not taxed again in the partners’ hands. The advantage of an LLP is protection, not tax savings.
Q8. What annual filings does an LLP have?
Form 11 is due by 30 May and Form 8 by 30 October. You must also file an income tax return, and DIR-3 KYC for designated partners.
Q9. When is an LLP audit compulsory?
When turnover is over ₹40 lakh or contribution is over ₹25 lakh. A tax audit may also apply under the Income Tax Act, depending on turnover.
Q10. What happens if an LLP does not file its annual returns?
Late fees are charged per day of delay, and they can become large. Continued default can lead to the LLP being struck off, and designated partners may face disqualification and penalties.
Q11. Can I convert my existing partnership firm into an LLP?
Yes. The conversion is done by applying in Form 17. Tax relief on conversion is available if conditions are met, so take advice from a CA first.
Q12. Are my personal assets completely safe in an LLP?
Generally yes, apart from your agreed contribution. But you stay personally liable for your own fraud or wrongful acts, and for any personal guarantees you sign for loans.
Q13. Do I need an LLP agreement?
Yes. It must be filed with the ROC within 30 days of incorporation. Without it, default rules of the LLP Act apply, which may not suit your needs.
Q14. What is a designated partner?
A partner who is responsible for the LLP’s compliance with the law, such as filings, and who carries penalties for defaults. Every LLP must have at least two, and each needs a DPIN.
Q15. Which is better for a small startup: a partnership or an LLP?
It depends on risk and plans. A very small, low-risk venture may start as a partnership. If you plan to scale, take loans, serve large clients or bring in more partners, an LLP is usually the safer choice. If you want venture funding, consider a Private Limited Company.
Read More About 👉 Registered vs Unregistered Partnership Firm
The Filing Zone is a trusted platform for business registration, GST registration in India, GST return filing in India, income tax return (ITR) filing in India, and other compliance services in India. We help individuals, freelancers, startups, and businesses simplify tax and legal compliance with convenient online assistance.
Our goal is to make compliance easier through professional guidance, transparent processes, and reliable support. Whether you are starting a new business or managing an existing one, The Filing Zone helps you understand your compliance requirements and complete essential formalities with greater confidence.
In this article we have shared about Partnership vs LLP: Which Business Structure Is Right for You? Understand the key differences, benefits, registration requirements, and compliance obligations before choosing the right structure for your business.
Need help with GST registration, ITR filing, or business registration? Visit The Filing Zone today to explore our services and get assistance with your compliance needs.